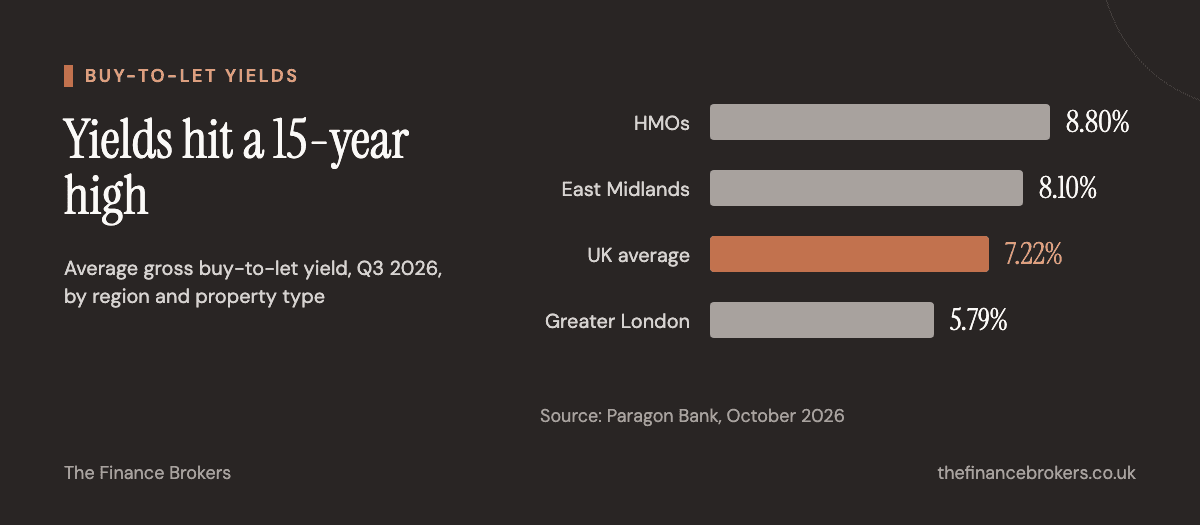
The average buy-to-let property in Britain now yields 7.22% a year in rent against its value. That is the highest figure since the first quarter of 2011, and it changes something more practical than a landlord's return on paper: how much a lender will let them borrow.
The number comes from Paragon Bank's latest yield research, published this morning. Yields rose 0.22 percentage points on the previous quarter and 0.28 points on a year earlier, and they have been climbing since 2022 as house prices stalled while rental demand held up.
Most commentary will read this as good news for landlords' returns. For anyone actually raising finance, the more useful reading is that rent, not deposit, is increasingly the thing that decides the size of the loan, and where you buy matters more than it has in years.
What Paragon found
The headline is the national average, but the spread underneath it is the real story. According to The Intermediary's report on the same research, average gross yields by region were:
- East Midlands: 8.10%, up 0.55 points on both the previous quarter and the year
- North East: 8.02%
- Scotland: 7.95%
- North West: 7.88%
- Greater London: 5.79%, the lowest in the country, though still up 0.23 points on Q2
And by property type:
- HMOs: 8.80%, the highest of any type
- Multi-unit blocks: 7.36%, up 0.34 points on the year
- Flats: 6.66%, with the fastest annual rise at 0.40 points
- Terraced houses: 6.46%
Louisa Sedgwick, Managing Director of Mortgages at Paragon Bank, put the rise down to "the balance between property values and rental income", adding that areas with more affordable values and sustained tenant demand "can offer particularly attractive yields."
That balance is exactly what a buy-to-let lender measures.
Why yield is a borrowing number, not just a return
A buy-to-let mortgage is not sized on the landlord's salary. It is sized on whether the rent covers the interest with room to spare.
The Prudential Regulation Authority's underwriting standards for buy-to-let set the framework most lenders still work to. The rent has to cover the monthly interest by a minimum ratio, and the PRA notes the industry standard minimum is 125%. That interest is not calculated at the rate you will actually pay. Lenders must allow for likely rate rises, including a minimum increase of 2 percentage points, unless the rate is fixed for five years or more.
Put those together and the yield on a property effectively caps the loan. The higher the rent relative to the price, the more of the price the rent can support.
What a 7.22% yield supports, region by region
Here is the arithmetic, using the averages above. Which? reported that the average fixed buy-to-let rate stood at 5.79% at the start of October, up from 5.47% in August. On a two-year fix, add the PRA's 2-point uplift and the lender tests the rent at around 7.79%. At 125% cover, the rent needs to be at least 9.74% of the loan.
So the maximum loan the rent alone supports, as a share of the property's value, works out roughly as:
| Average yield | Loan the rent supports (2-year fix, illustrative) |
|---|---|
| HMO, 8.80% | about 90% of value |
| East Midlands, 8.10% | about 83% |
| National average, 7.22% | about 74% |
| Flats, 6.66% | about 68% |
| Greater London, 5.79% | about 59% |
In practice most lenders cap buy-to-let at 75% or 80% loan to value regardless, so the table tells you which limit bites first.
Outside London, at today's yields, the rent test is no longer the main constraint for many properties. An HMO or an East Midlands terrace at its region's average yield clears the rent test comfortably at a normal deposit. The binding limit is the lender's maximum LTV.
In London it is the other way round. At a 5.79% yield, the rent supports only around 59% of value on a two-year fix, so a London landlord can have a 25% deposit ready and still be offered less than they asked for. They need a bigger deposit, a longer fix, or a lender that treats their case differently.
These are illustrative averages, not quotes. Individual lenders set their own cover ratios and stress rates, personal-name borrowers paying higher-rate tax are often tested at a higher ratio, and an actual property's rent and valuation will differ from its region's average.
Why the length of the fix now matters more
The PRA's five-year exemption is where this gets interesting. If the loan is fixed for five years or more, the lender does not have to apply the 2-point uplift, so the rent can be tested much closer to the rate being charged.
Run the national average again at 5.79% with no uplift and the rent supports close to 100% of value, meaning the LTV cap is the only limit. Run London again and it rises from about 59% to about 80%.
That is a large difference in borrowing power from a product choice alone. It is also why the same landlord, with the same property, can get very different answers from different lenders. Some lenders apply their own floor or a higher ratio even on five-year fixes, and some price longer fixes less keenly. Rates are moving too: the average five-year residential fix reached 6% according to Moneyfacts on 5 October, the highest in about three years, and buy-to-let pricing has started to follow it up.
What this means if you are buying or refinancing
If you are buying outside London, today's yields mean the rent is doing most of the work. Focus on the deposit and the lender's LTV limit, and make sure the rental valuation is properly evidenced, because that is what the lender will lean on.
If you are buying or refinancing in London, expect the rent test to bind. A five-year fix, a limited company structure or a larger deposit may each change the answer, and it is worth knowing which before you agree a price.
If you run HMOs or multi-unit blocks, the higher yields help, but these are specialist products with their own criteria. The lenders who understand them are not always the ones with the sharpest headline rate. The specialist end of the market has been competing hard for professional landlords this year, and that competition is worth using.
If you are coming off a bridge onto a buy-to-let mortgage, the refinance is now sized as much on the achieved rent as on the value. Get the tenancy in place and evidenced before you apply. Our guide to remortgaging after a bridging loan walks through how that exit works.
The bottom line
A 15-year high in yields is a sign that rents have outrun prices. For a landlord raising finance, that turns into borrowing capacity outside London and a tighter rent test inside it, with the length of the fix doing more to move the answer than most borrowers realise.
As a whole-of-market property finance broker, we can run your property's actual rent and value against the cover tests lenders really use, across portfolio, HMO and commercial mortgage lenders, and tell you which limit bites first. If you have a purchase, a refinance or a bridge to exit, get in touch.
Further reading: Buy-to-Let Rates Are Falling: Paragon, Shawbrook and TML All Cut, our June look at where buy-to-let pricing was heading before swap rates turned.